Alpha Casts - AI Market Intelligence

Your daily dose of stock market analysis from StockAlpha.ai. We break down market sectors, cover breaking financial news, and highlight investment opportunities you need to know about. Perfect for your commute, workout, or whenever you want market intelligence on the go.
$NVDA — Nvidia’s Record Beat Meets a Market Still Testing Its Appetite for Risk
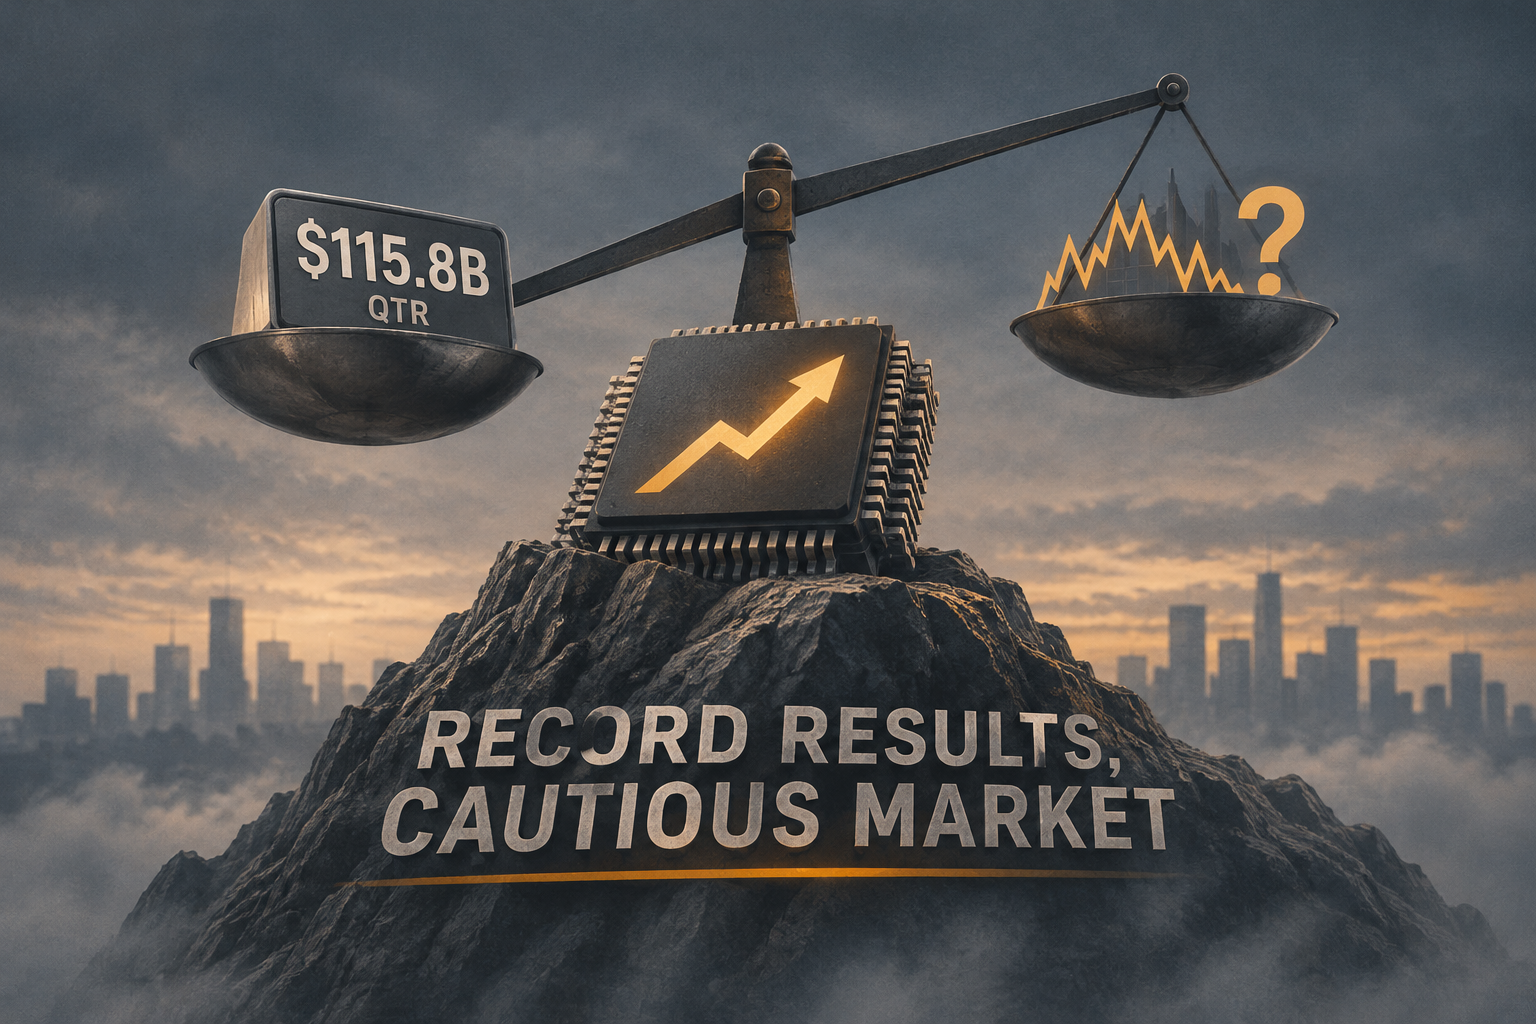
$NVDA — Nvidia delivered a $115.8 billion quarter and guided to $130 billion, yet shares rose only 2.4% after hours—far short of the 8%–10% move implied by options. Across the day’s reports, record AI demand competed with signs of sector rotation, a possible higher-rate path, softer retail momentum, and several sharp company-specific moves.
Home Depot’s Leadership Shift Leads a Day of Big Promises—and Few Hard Numbers
$AAPL $GS — Home Depot paired a CEO succession with a higher sales outlook, while Goldman Sachs signaled confidence in the S&P 500’s 2027 prospects. A possible Apple-Samsung DRAM deal and a wave of AI and infrastructure announcements added to the day’s themes, but many updates lacked financial terms or evidence of near-term business impact.
$NVDA — Stocks Retreat Ahead of Nvidia Results as Small Caps Lead the Decline
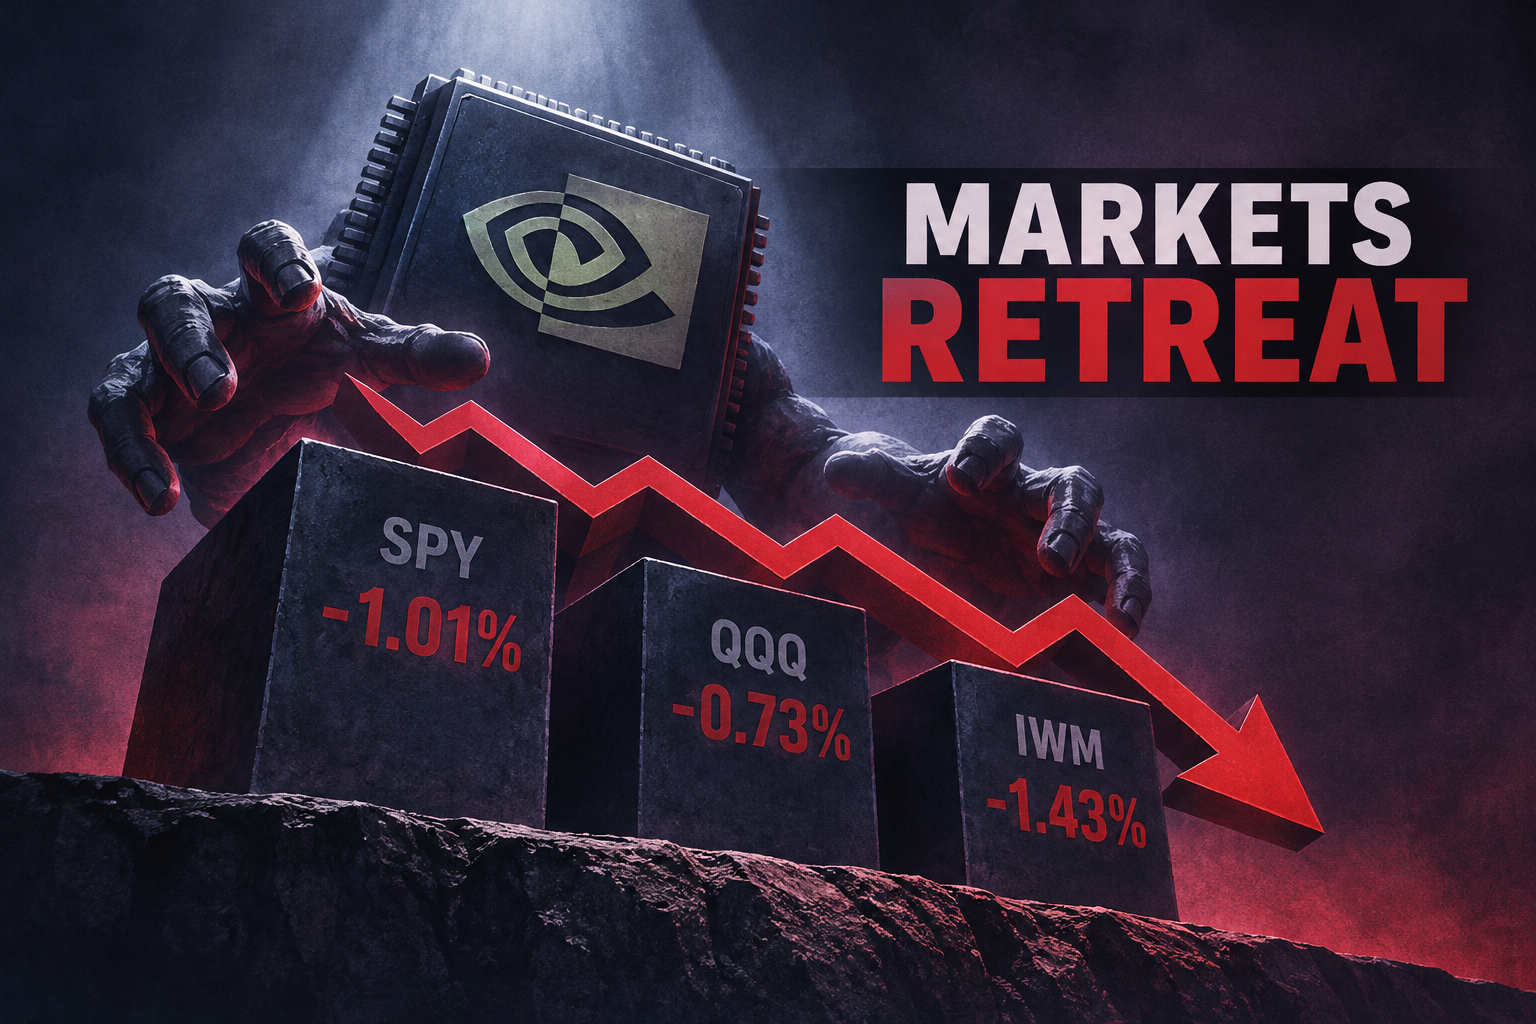
$SPY $QQQ $IWM $NVDA — U.S. equities fell on November 17, with the S&P 500 ETF SPY down 1.01%, the Nasdaq-100 ETF QQQ off 0.73%, and small-cap IWM losing 1.43%. Investors approached Nvidia’s results with markets under pressure, while headlines pointed to mixed sector-specific forces and no supplied economic release to clarify the near-term outlook.
Sector Signals Split Between AI and Energy Investment, Credit and Demand Risks
$BTC — The Nov. 17 sector summaries show a market defined by sharply mixed company and policy signals, rather than a clear performance leader: reported returns were unavailable across all sectors. Project advances in materials, healthcare and energy contrast with housing affordability pressure, crypto weakness and operating risks across communications and utilities.
Growth Is Visible; Valuation, Financing and Data Quality Set the Terms
This week’s broad research slate found operating momentum across AI infrastructure, energy, software and healthcare, but positive earnings surprises rarely settled the valuation question. Debt, capital spending, cyclical exposure and inconsistent market data repeatedly tempered constructive company-specific narratives. The overall reading is neutral: near-term catalysts are numerous, while confidence in some supplied estimates is not.
$TSLA — Tesla’s €3 Billion Berlin Bet Leads a Day of Big Plans—and Bigger Unknowns
$TSLA $BA — Tesla’s proposed expansion in Germany was the day’s clearest strategic market story, while Boeing touched a 52-week low and new legal notices put Caterpillar and Bank of America under scrutiny. Across technology, finance and healthcare, many announcements pointed to growth ambitions but offered little evidence yet of measurable financial impact.
$BTC — Markets Split Between AI-Linked Risk, Crypto Weakness and Sector-Specific Growth Catalysts
$BTC — Nov. 16’s sector summaries point to a divided market: technology and crypto face visible pressure, while healthcare, materials and consumer businesses offer a mix of product, deal and investment catalysts. The available reports contain almost no sector-level return data, so the day’s strongest and weakest groups can be assessed only by news flow—not ranked by actual performance.
$POET CEO Q&A: The Bottleneck Is the AI Bull Case
$POET — $POET CEO Q&A: The Bottleneck Is the AI Bull Case
$POET Reported Into a Red Tape. Don't Blame the Print
$POET — $POET Reported Into a Red Tape. Don't Blame the Print
Sharp Single-Session Swings Meet Thin Evidence as Markets Head Into the Weekend
$ICE — Friday’s reported trading featured a 142.47% surge in FCUV, a 10.97% drop in leveraged semiconductor ETF SOXL, and a large but inconsistently reported gain in SHFS. The analyses offer little explanation for the moves, while a separate policy report about ICE activity reporting raises questions for social platforms without establishing a direct financial impact.
Friday’s Market Whiplash: Sharp Selloffs, Penny-Stock Surges and Questions Over the Data
$NVDA — Friday’s final U.S. session delivered a mix of steep declines and explosive rallies, with Paysafe’s lowered revenue outlook and a sharp drop in Nvidia among the more consequential company-linked stories. Many of the biggest percentage moves involved low-priced shares or warrants, and several reports lacked a confirmed catalyst or contained conflicting quote data.
AI Momentum Meets Higher Yields and a More Demanding Earnings Test
$NVDA — The day’s analyses point to a market balancing persistent AI infrastructure demand against rising rate pressure, uneven corporate signals and slower earnings-surprise momentum. A sharp conflict in reporting about Nvidia leadership underscores why investors may need to separate confirmed developments from claims that remain unresolved.
$DKNG — DraftKings’ 25% Slide Leads a Day of Accounting and Controls Warnings
$META $DKNG — DraftKings fell nearly 25% after disclosing that planned investment in its Predictions business would double, while a $659 million goodwill impairment and construction-cost control problems brought fresh scrutiny to other companies. Elsewhere, Meta tested a prediction-market app and healthcare AI adoption remained a longer-term theme, but many announcements offered limited evidence of near-term financial impact.
Tech-Led Weakness Pulls $QQQ Lower as $U.S. Stocks End Nov. 13 in the Red
$QQQ $SPY $IWM — U.S. equities finished lower on Nov. 13, with the Nasdaq-100 ETF (QQQ) down 1.20% and the S&P 500 ETF (SPY) off 0.36%. The Russell 2000 ETF (IWM) slipped 0.32%, while a crowded set of industry and company headlines—from AI spending to consumer pricing—left the next session’s direction dependent on fresh evidence.
AI Demand Meets Risk-Off Pressure as Sector Signals Diverge
$BTC — Nov. 13’s sector headlines offered no comparable price-return data, but they revealed a sharp split in the market narrative: AI and infrastructure investment continue to generate growth catalysts while crypto, energy, and policy-sensitive industries face meaningful risks. The clearest cross-sector themes were the cost of building capacity, regulatory uncertainty, and the gap between long-term demand prospects and near-term execution.
5 Storms Hit AI Stocks in One Week. Who's Built to Last?
5 Storms Hit AI Stocks in One Week. Who's Built to Last?
Yields Above 5% Recast the Risk Landscape as AI and Small-Cap Stories Diverge
The 10-year Treasury yield’s return above 5% and reports of the sharpest bond-yield surge since 2022 put financing costs and valuations at the center of the day’s market debate. At the same time, AI-related companies posted contrasting signals, while housing data and scattered stock moves underscored how uneven the market remains.
AI Infrastructure, Big Financing and Legal Risk Lead a Crowded News Day
$GOOGL — A proposed 100-MW GPU data center in Kazakhstan and fresh capital for renewable development put infrastructure and funding in focus, while legal notices involving Alphabet and UnitedHealth add a note of uncertainty. Most announcements offered no confirmed public-company revenue impact, leaving execution, deal terms and follow-up disclosures as the key signals to watch.
Small Caps Lead a Broad Retreat as Treasury-Yield Concerns Keep Pressure on Risk Assets
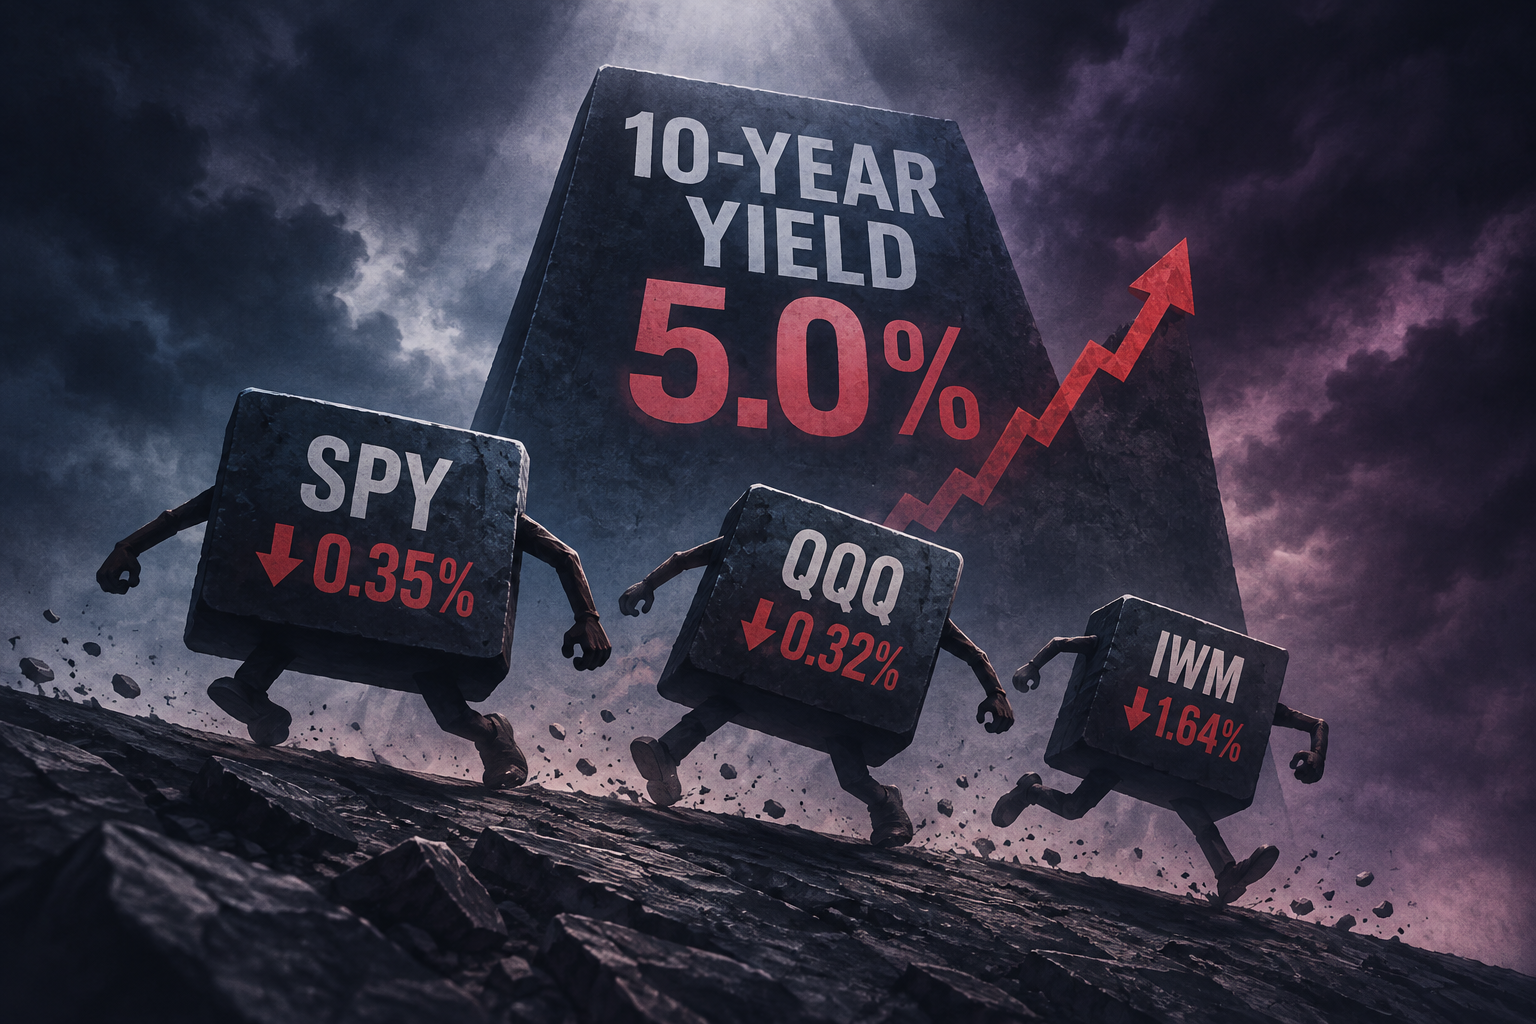
$SPY $QQQ $IWM — U.S. equities ended lower on November 12, with SPY down 0.35% and QQQ off 0.32%, while the Russell 2000 ETF IWM fell a sharper 1.64%. A market-event roundup highlighted a 10-year Treasury yield touch of 5%, mixed sector signals, and a handful of sharp single-stock moves; no specific economic release or sector-return data was provided.
Policy, AI and Financing Risks Divide the Nov. 12 Sector Landscape
$BTC — Nov. 12’s sector briefings point to a market shaped by competing forces: investment in AI, infrastructure and healthcare innovation on one side, and crypto outflows, governance concerns and policy uncertainty on the other. Because the summaries provide no sector-return data, actual leaders and laggards cannot be ranked; the recap instead compares the day’s reported catalysts and risks.
Avicanna $AVCNF Turns EBITDA Positive After Ottawa’s Cut
$AVCNF — Avicanna $AVCNF Turns EBITDA Positive After Ottawa’s Cut
AI Bifurcation and Rate Risk Drive Rotation: CoreWeave Rally, $POET Pin Fight, and an Inflation-Fueled Reweighting Toward Quality
$POET $BRK.B — CoreWeave’s blowout Q3 and a sharp intraday rally set the tone for renewed AI optimism even as broader AI names slid, sending Berkshire to its widest lead versus the S&P since 2010. Options positioning around POET ahead of its Q3 release and Fed officials’ hawkish comments on inflation make this a high‑volatility, event‑driven market.
$GOOGL $PYPL — Tech funding, chip-share shifts and rising regulatory risk drive markets — Alphabet bond, server-CPU momentum and PayPal probe lead the day
$AMD $GOOGL $META $PYPL $ARM — Alphabet explores a $3B Asia bond while UBS spotlights server-CPU strength that benefits AMD and Arm — yet regulatory probes (PayPal, Meta-related youth-safety push) and fresh litigation/leadership shocks (Fluence, Honeywell reminder) keep volatility elevated. Today's flow shows capital markets activity, a semiconductor share shift, and intensifying regulatory/legal headlines to watch.
Tech-Led Rally Propels Benchmarks Higher as AI Earnings and Energy Trends Drive Risk-On Sentiment
The S&P 500 and Nasdaq-100 climbed on strong tech earnings and sector rotation into energy, materials and grid-tech utilities. CoreWeave’s blowout quarter and renewed demand signals across energy and materials helped lift markets, while the Fed’s path remains the key macro watch for traders.
Market Crossroads: AI, Energy Transition and Policy Risk Drive Mixed Sector Tape on Nov. 11
$BTC $MSOS — A day of bright spots and headline risks left markets segmented: utilities, healthcare and materials showed clear momentum while crypto, finance and cannabis wrestled with policy and liquidity shocks. Data and regulatory signals — from a rare advanced-nuclear NRC permit to a $14.2B stablecoin outflow — set the tone for a cautious near-term rotation.
$POET Gamma Map: The Run to $5.74 and the $5.50 Pin Fight
$POET — $POET Gamma Map: The Run to $5.74 and the $5.50 Pin Fight
LWLG Earnings: The Stock Got Hit for Telling the Truth
LWLG Earnings: The Stock Got Hit for Telling the Truth
$AAPL — Hot CPI, 10-Year Yield Above 5%, and a Mixed AI Tape: Markets Grapple with Rate Risk, IPO Demand, and Debt-Fueled Growth
$AAPL — A hotter-than-expected CPI print and the 10-year Treasury reclaiming 5% set a risk-off tone, even as AI headlines — from CoreWeave raising guidance to Anthropic's IPO range — deliver mixed signals about demand and valuation. The day highlights a tug of war between rate-driven macro risk and sector-specific developments tied to AI, leverage, and product innovation.
AI Assurance, Asset Outflows and an Early Airport: Key Market Moves from Nov. 10, 2026
$IBM — Today’s headlines ranged from Western Sydney International opening seven months early to Invesco reporting a 3.3% AUM drop and IBM cutting visa/green-card sponsorship in consulting. A recurring theme: standardization and third‑party assurance in AI and security, even as flows and talent-policy shifts create near‑term execution risks for big corporates.
Yield Spike and Mixed Earnings Drive a Risk-Off Pulse — Tech Weakness Leads Broad Market Pullback
$SPY $QQQ $IWM — Stocks slipped as hotter inflation readings and a jump in Treasury yields knocked growth names lower. The S&P 500 (SPY) fell 0.37%, the Nasdaq-100 (QQQ) dropped 0.68% and small caps (IWM) also declined 0.68%, while pockets of defensive strength and idiosyncratic earnings paint an uneven near-term picture.
Mixed Macro, Clear Secular Bets: AI, Renewables and Real Estate Shine Amid Policy and Rate Headwinds
$BTC — Markets closed out a day of cross-cutting narratives: heavy policy and regulatory noise collided with steady capital deployment into AI, renewables and logistics. Bitcoin slipped under $74,000 after hotter CPI data, while mortgage rates eased to 7.35% and real-estate leasing picked up steam—leaving a bifurcated market where tactical risk management matters.
AI Capex, Energy Momentum, and Income Versus Leverage: Key Research Signals from a Week of Earnings and Thematic Re‑rating
This week's Alpha Research cycle reinforced two structural narratives — AI-driven capex that is re‑rating semiconductor and data‑center supply chains, and energy midstream/refining strength underpinned by commodity moves — while income-oriented names trade with elevated leverage and limited analyst upside. Below: a thematic synthesis, grouped summaries with specific data points, cross‑cutting patterns, contrarian reads, methodological notes, and a concise research agenda for next week.
Inflation, Rotation and Realignment: Markets React to Hot CPI, Corporate Moves and The AI Trade’s Changing Footing
$AAPL — A hot CPI print and fresh corporate actions — from Apple’s $2.7B tax shift to PepsiCo job cuts and Goodyear’s CEO exit — set a cautious tone as sector rotation away from concentrated AI winners collides with pockets of analyst-driven optimism and tokenization momentum.
Litigation Ripple, AI Alliances and Energy Sector Jitters Dominate Today's Market Briefs
$GOOGL $BAC $DIS $ADBE $NTRS $MSFT — A flurry of securities actions — including suits tied to Alphabet (GOOGL), Bank of America (BAC) and Fluence Energy (FLNC) — drove headline risk today, even as major AI partnerships (Disney (DIS) & Adobe (ADBE), Northern Trust (NTRS) & Microsoft (MSFT)) and infrastructure-policy moves reshaped forward-looking operational narratives. Read a thematic take on what moved markets and what to watch next.
Broad Risk-On Rally: Tech Leads as Small Caps Keep Pace; Markets Push Back on Rate Angst
$SPY $QQQ $IWM — Stocks rallied across the board as the Nasdaq-100 outperformed, SPY climbed 2.37% and QQQ jumped 3.54% while small caps (IWM) also posted a strong gain of 3.23%. Sector rotation and a string of corporate headlines drove a broad advance and shifted near-term policy bets.
Mixed Market Momentum: AI Product Pushes and Industrial Capital Flows Clash with Geopolitics and Regulatory Noise
$NVDA $MSOS — Markets closed the day with a mixed tape: technology and industrial flows showed clear momentum driven by AI product launches and big raises, while energy, communications and cannabis felt the drag of geopolitics and regulatory/legal headlines. Investors should watch CPI, the Nvidia board probe, and several regulatory developments for cross‑sector spillovers.
$POET Q3 Preview: $700K to $2.5M Is a Shrug, Not a Consensus
$POET — $POET Q3 Preview: $700K to $2.5M Is a Shrug, Not a Consensus
Breadth for Beginners: When the Index Is Up but Most Stocks Are Down
Breadth for Beginners: When the Index Is Up but Most Stocks Are Down
Market Bifurcation and Volatility: Mega-Cap Resilience vs. Semiconductor Stress Headline the Holiday Weekend
$NVDA — A sharply bifurcated tape dominated the session: mega-cap techs held up while semiconductors showed acute stress — NVDA plunged 8.91% as SOXL surged 12.43% on heavy turnover. Meanwhile, OpenAI’s expansion plans and a flurry of small-cap value screen entries add policy and idiosyncratic catalysts into an already fragile liquidity backdrop.
$DKNG — Volatility Rally: TQQQ Sells Off, DraftKings & Koppers Draw Legal Scrutiny — Penny Stocks Explode Ahead of Long Weekend
$DKNG — A volatile Friday closed with leveraged ETFs tumbling, investigation notices for DraftKings (DKNG) and Koppers (KOP), and a wave of outsized moves across microcaps and penny stocks. Traders face elevated weekend gap risk; watch filings, volume, and tech/leveraged-product flows when markets reopen Monday.