Capital Flows and Asset Markets
Explaining how capital flows and asset markets work www.russell-clark.com
IS OIL A BETTER INFLATION HEDGE THAN GOLD?
I have been a little blindsided by the move in GLD/TLT this month. Gold has gone down, and TLT has gone up. Technically, GLD/TLT has gone through its 200 MDA, and the 200MDA is threatening to turn lower for the first time since 2020.
It has returned 500% from 2020, so maybe this trade is done? Using a longer time series, its feels like a correction.
But the point of GLD/TLT is that they should be broadly speaking positive correlated, so when TLT is doing well, GLD should do well and vice...
SITUATIONAL AWARENESS - GOOD IDEAS, BAD RISK MANAGEMENT
In my old fund, I used to hire summer interns. Like everything I do in my life, I looked at the results, and then try and improve the outcomes. When we first started, we asked for CVs first and then did interviews. This process sometimes worked, and sometimes didn’t. The interns that seemed great on paper and interviews, were just not great investors. One summer I changed the process, and I asked potential interns to write 200 words on an investment idea. I also asked them to submit the idea with just the mobile phone number, so we had no...
AI AND ANTHROPIC MAKE ME THINK YIELDS ARE GOING HIGHER
While I do believe you should never start with the idea that “equities are wrong”, when I see the performance of AI hardware against software companies this year I do laugh. Was it really only June when all software stocks were toast, and you HAD to be in hardware stocks? This trade has roundtripped.
I did find this amusing, until suddenly this month, the bond markets started to think the travails of Coreweave and other AI stocks was a deflationary event. Japanese 30 year yields fell nearly 40bp this month, and back to trend line...
OCTOBER - “AXE TO FOREHEAD” MONTH
Many years ago I met a short only fund manager at a conference. He was a highly strung character, who constantly checked his phone. Someone asked what do you do when someone acquires a company you are short. It was a good question I thought - you would be surprised how often this happens, often by a company you are long off. His comment - which has stayed with me all these years - is that when this happens, it is “an axe to the forehead - an occupational hazard”.
Now I don’t beli...
ARE THESE MARKETS MACRO OR POLITICAL?
I have been looking at markets, and wondering why something like GLD/TLT looks like the SOX. GLT/TLT below.
And here is the SOX.
I know that the macro guys are super bearish. And they are bearish because of credit. We have French CDS.
And we have Coreweave CDS
So the macro view, and why markets are getting pummelled is that the markets are telling France to cut spending or raise taxes, and the market are telling Coreweave to raise equity and cut capex. This signal is so...
IS IT THE END OF AI - OR JUST THE FINAL UNWIND OF SITUATIONAL AWARENESS?
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
Everywhere I look in markets is pricing the end of the AI trade. It is even turning up in sovereign bonds, with yields now falling, after rising for most of the year. I find it a bit odd, as every physical commodity price I look at is still going up. The issue here is that you have to be sure that equities are accurately pricing the future. SK Hynix has typically been pretty responsive to spot DRAM prices. Not...
SHORT SELLING WEALTH WARNING
I have written about AI and Coreweave a lot in the last few days. And I have received a lot of replies, almost universally bearish, and from a lot of managers and investors that I respect. And to be honest, if gives me pause. So I thought I should give some more detail on how I think. I am not a short term trader. When I go bearish on something, I expect it to fall for quite some time. I look at both demand and supply, and basically figure out when profits in an industry are going to go...
THE TRUE MEANING OF COREWEAVE
(Apologies for this post - it is slightly more stream of consciousness that I like, but it is my thought process. Will follow up with more clear logic)
When something does not make sense to me, my subconscious keeps nagging away at me. Generally speaking I trust my subconscious - its gets things right. If I wake up in the middle of the night, worried about a position, then I know its probably too big or just wrong. My best positions, both long and short are always when I am so excited, I just need to get...
THE DRAWBACK TO POLITICAL ANALYSIS OF MARKETS
My investment process is built around looking at how other investors have made mistakes from time to time, and then building a process to avoid that mistake, and if possible to profit it from it (which is big driver of my shorting process). In my first half of my career, I was heavily macro, as I found currencies were the main driver of investor mistakes. I did my best to quantify this process by formalising the use of NIIP and BIS cross country data. I think I was one of the first investors to do this. But...
GLD/TLT AND COREWEAVE
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
I had barely sent out an update on GLD/TLT when market action has come to test me. If you have been living under a rock, the AI trade has swooned as the bonds of Coreweave has been sold aggressively. They are now yielding 15%, or perhaps more importantly, as a big discount to par - signalling fears of default.
I took a good look at Coreweave, and came up with two totally different outcomes. In one we enter a...
WHERE ARE WE WITH GLD/TLT?
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
Years ago when I came up with GLD/TLT, I thought it was a great trade - but super simplistic. So simplistic, I thought people would laugh at me. But I have been pleasantly surprised at how many people have been influenced by this trade. I have even seen people use it in their own research. Now this is all great and dandy, but I had another investment catchphrase back in the day - “long bonds/short equities” which worked great, unti...
END OF THE AI TRADE?
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
Back in 2025, I shorted Nvidia on the back of the DeepSeek LLM model - but fortunately covered at a profit. It seemed very logical to me that the appearance of a much cheaper LLM model should be deflationary across the whole AI stack. But this analysis was wrong.
Today, we are seeing another sell off in tech, on the back of announcement that Chinese chip company CXMT has made a breakthrough in memory chips.
To...
IS SHORT TLT DONE?
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
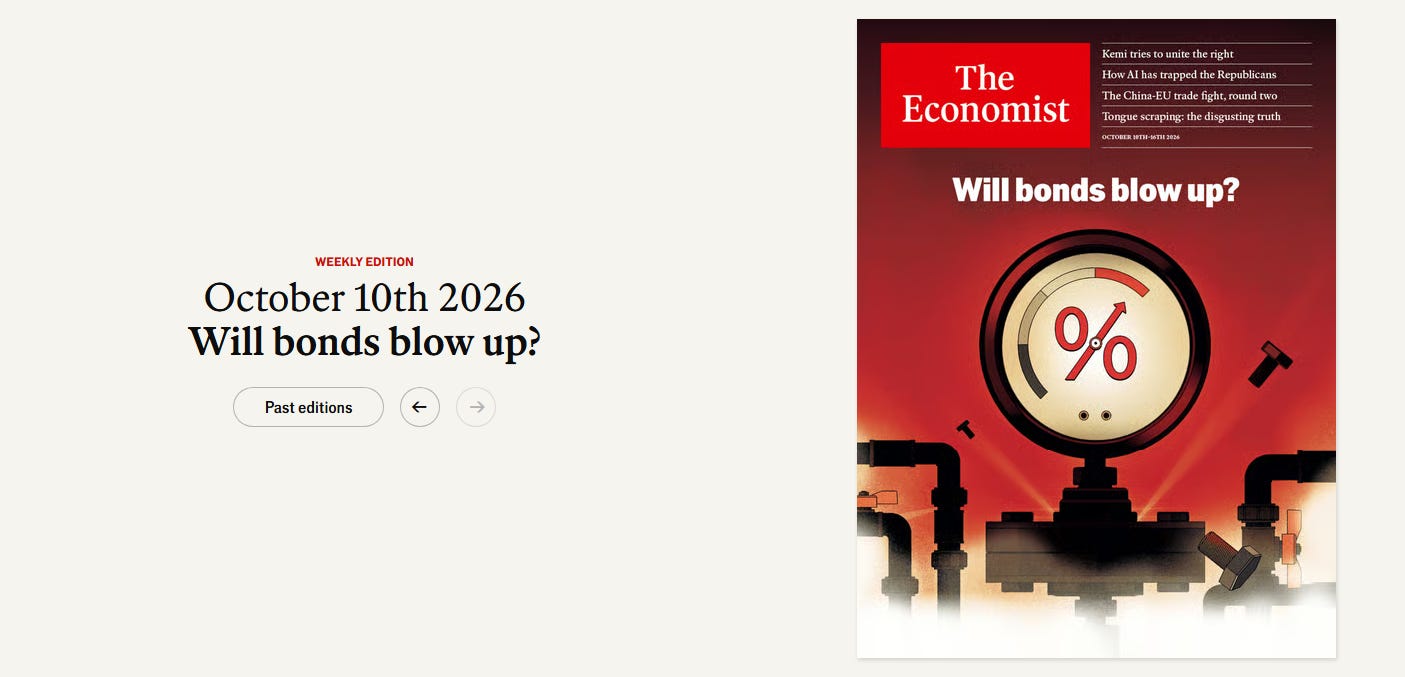
There is a widely held belief that the cover of the Economist is a contra indicator. The Economist itself also covers this question in an article. The quantitative analysis concludes no. For me, I feel like the cover is too narrow. I feel you need to read the main lead article to see what their logic is to really get an idea of it contra indicator ability. For me, reading the article, it feels generally good news I think, as least...
AI AS A MACRO FACTOR
( I sat down today to try and work my way through the AI conundrum - below is a stream of consciousness style analysis - I suspect some with think me insane, and some will think me genius. Time will tell.)
The weird thing about the AI boom is how familiar it seems to me. Back in the day, I made my name shorting mining and emerging markets, based on a very simple observation. I was looking at Chinese production of steel rising almost continuously from 2000.
But I noticed from 2008 onwards, Chinese steel companies share prices...
WHY ARE MACRO INVESTORS SO DUMB?
Without question the worst investors over the last ten years have been macro investors. The one trade I probably talk about the most on this substack has been long Yen, which I now call the widowmaker trade. There was a time when Yen would rally when US stocks were weak - but not anymore.
Another foolish trade from the macro community is that higher Japanese and US bond yields would have some sort of negative effect on US stock valuations. Very wrong indeed.
Macro investors used to insist that large fiscal deficits would lead to...
SEPTEMBER REVIEW
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
September was a long month - but a satisfying month. It proved, to my mind at least, that political analysis is superior to old school analysis. First and foremost in this was the merit of GLD/TLT. I think many “investors” and “macro commentators” find it much easier to go all in on debasement trades. But politically I found it much more difficult. There is always the chance that politics or circumstances forced central banks and governments to run much tighter money th...
FRENCH LESSONS
In case you have been living under a rock, French bonds have been under pressure. Typically, sovereign bonds cannot default, but with European bonds there is a risk that you are forced to leave Eurozone, so with European bonds, CDS can actually work as an indicator. French CDS have soared in recent weeks.
France has a lot of debt - but so do most countries. But it does have a budget deficit that is very high by European standards. 3% is the supposed limit.
One of the weird things about the “French bond crisis” is that unti...
THOUGHTS FROM SWITZERLAND
I just got back from a couple of days in Switzerland, where I spent most of my time talking about markets. I also met quite a few Substack subscribers. Here are my thoughts.
SUBSTACK
Substack tells me that my average article gets 8,000 views. I thought this was exaggerated as the usual 10 to 15 people are commenting on it, and a typical article now only generates maybe 5 or 10 new subscribers. I suspected that number of people that actually read my substack was lower than what I was told. This trip has made me think the...
WHEN DOES THE BOND MARKET BUCKLE?
I will be at the NZZ bar from 4.30 to 6pm at Zurich HB tomorrow, and Café Tartines - Champel in Geneva from 8am to 9am on Wednesday if you would like to say hello.
I have tended to make fun of “macro” analysts on this Substack - mainly because they are such easy targets. One of their consistent problems is that they apply economic or accounting logic to sovereign bond markets. Through the mega bull market in bonds, were bearish all the way up (or as yields went lower). Short JGB trade was called the widow...
HIGHER YIELDS ARE NOT IMPLYING DEFAULT RISK - AT LEAST NOT YET
Much as been made of the US 10 year bond yield pushing through 5% for the first time since 2007.
And much has been made of the fact that net interest payments are much larger than defence payments, and closing in on social security payments.
But a weird thing is happening. The US tends to devalue when it is bust. Back in the 1970s, the value of the US dollar collapsed against the Swiss Franc, and again in the 2010s. But as of today the Swiss Franc is around the level it reached back in 2011, and is actually...
HAVE CENTRAL BANKS ALREADY LOST CONTROL OF CREDIT MARKETS?
How you feel about central bank policy making since the appearance of Ben Bernanke around 2000, will pretty much determined by your positioning in asset markets. Private equity love him. Renters not so much. But one think that Ben Bernanke certainly introduced to markets was asymmetrical policy making. Helicopter Ben was all about big dramatic cuts and interventions to the downside, and then only inching up rates when growth returned. 2022 was a return to central bank surprising hawkishly, but since then, its been a return to cutting interest rates whenever possible.
This asymmetry of central bank policy making...
MACRO AND THE PRO LABOUR TRADE
Markets are about greed and fear. Greed is easy to understand, but fear is more difficult concept. One way fear shows up is in a rejection of something new, and this in particular appears in older investors. I have a lot of sympathy for this fear. In the markets I grew up in, crises and crashes were the norm - not rare events. Japanese bubble burst 1991, the Tequila crisis in 1994, Asian Financial Crisis in 1998, Dot Com Bust in 2000, Latam Devaluations of 2001/2, GFC in 2007/8, Eurocrisis of 2011, EM problems of 2015/6. To survive in markets, being paranoid and cynical was a prerequisite.<...
A REVERSE GFC?
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
Getting old has pluses and minuses. One recent plus is I can finally play some decent tennis, its only taken 15 years of work! One recent negative is I can only maintain a high standard for one set before getting tired. C’est la vie.
I mention this as we move closer and closer to the 20 year anniversary of the GFC. 20 years is a long time. When I started working people were still talking about Black Monday, 19 October 1987. I remember in...
WHY LONG/SHORT HEDGE FUNDS ARE NO GOOD ANYMORE
I was lucky enough to start working at GAM in 2002. GAM was a leader in the fund of hedge fund business just as it was booming. The source of this success was not hard to find, and being at GAM was a great place to see it. The dot com bubble was coming to a head in 1999 - and as one investor told me - funds had to sell value stocks to buy growth stocks or risk underperforming. This Morgan Stanley Growth v Value index gives an idea of how extreme it was.
Many of the hedge...
THE TREAURY BUYBACK IS TOO SMALL
One of Prime Minister Abe’s aim was to get Japanese investors to stop being conservative. He was particularly keen on getting Japanese investors out of JGBs. The main was was to get the Bank of Japan buying basically the entire JGB market. In USD terms, the BOJ balance sheet went from USD 1.7tn to about USD 7tn
And this has led to Japanese investments in domestic bonds falling dramatically. In other words the BOJ bought bonds of JGB investors at a very high price.
The good news for Japanese investors is that they sold mo...
OBSERVATIONS ON CURRENCIES
Like almost everything in my life, if something works, then I keep using it, but when it stops working, I move on. Currencies used to be so reliable in finance, I build my whole investing process around it. I am provoked to write this note, because the Korean Won has just had a straight line 15% move.
What is noteworthy for me, is that for the life of me, I could not understand why Korean Won was at all time lows to start with. Korea has a cyclical currency, which tends to follow equity markets. It also tended...
WHAT TO DO ABOUT THE YEN? PART 2
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
I decided to get in to finance in 1998, when living in HK. I was fascinated at how currencies, interest rates and equities were so tightly bound, and this fascination led me to a hedge fund career. You can read about it my book. In my experience, politicians often intervene in the value of their own currencies. Either to weaken it or strengthen it. Plaza Accord was a multinational accord to weaken the USD for example. And then you have currencies pegs...
WHAT TO DO ABOUT YEN?
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
The BUY case for Yen is straightforward. As millions of tourists will happily tell you Japan is cheap. Using the BIS real effective exchange rate measure, the Yen has collapse in value. This measure takes in relative inflation AND exchange rate - so makes the Yen even cheaper than just looking at straight exchange rates.
I have in previous post called “long Yen” the Widowmaker trade. It used to be short JGBs were the widowmaker trade, as vari...
IS IT THE END OF THE ROAD FOR GLD/TLT?
First a bit of housekeeping - I will be in Zurich and Geneva on the 29th and 30th of September. If you would like to catch up - drop me a line.
Also I am trying Substack video for the first time - feedback appreciated.
When I first came up with the idea of GLD/TLT, it was so simple and so obvious, I was almost ashamed to publish it. But as old boss once told me, simplicity breeds elegance. And I do like to be elegant. GLD/TLT has been good, and its bounced...
DO RISING YIELDS ACTUALLY AFFECT STOCKS?
I have been pretty sure that bond yields would keep rising, mainly because governments are going to keep spending. But I did think rising bond yields would act as a break on equity valuations. This is very typical in emerging markets, where high interest rates and bond yields have tended to depress equity valuations. Brazil is a good example, where it has historically had high interest rates, mainly due to high inflation rates.
In 2020, interest rates reached an all time low, and then rose again. Using Price to sales, the Bovespa traded at its highest...
WTF? WAFERS, TOO FAR?
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
After the surge in DRAM and NAND prices, I thought wafer prices would be the next to go. For context, DRAM prices remain substantially higher than a year ago.
If you want an industry primer on wafers, have a look at this note from Brevarthan Research. So what has been going on in the wafer space?
AUGUST REVIEW
The most pleasing aspect of August was the rally in GLD/TLT to recapture the 200MDA. My view on this is that this will continue to do well until rising bond yields forces the US government to take fiscal deficits seriously. The two big events of the month was that the US Treasury tried to control bond yields rather than control spending (expected and good for gold) and that the Federal Reserve was more hawkish than anticipated (also expected and bad for gold, but also bad for bonds). I did wonder what happens to GLD/TLT when Donald Trump...
IS IT TIME TO SHORT SELL?
This is a free preview of a paid episode. To hear more, visit www.russell-clark.com
The big market news over the summer was the unwind of the momentum trade. The Goldman Sachs High Beta Momo Index suffered a 42% drawdown, and the dead bodies in hedge fund world have slowly been rising to the surface.
While everyone knows that memory stocks in particular got smashed, the above MoMo index is made up momentum longs AND momentum shorts. Momentum shorts generally work. That is falling stocks have a habit of keep falling. But was has been...
日本が米国債について教えてくれること
ここ1か月ほどの間に、米国は2つの異なる市場介入を発表した。
ひとつは長期米国債市場への介入で、国債の買い戻し(buyback)を拡大するというものだ。もうひとつは為替市場への介入で、円高を促すUNAGASUためのものだった。
長期債市場への介入は比較的理解しやすいし、過去にも例がある。ただし、これまでのところ債券利回りには特に変化は見られていない。
一方で、円への介入のほうが興味深い。こちらは少なくとも、市場に目に見える動きをもたらした。
しかし、そもそも円高がどのように米国債市場を助けることになるのだろうか?
私には、この円介入は「もはや存在しない世界」に市場を戻そうとする試みCOCOROMIに思えてならない。
では、その「世界」とはどのようなものだったのか。
1990年から2016年にかけて、日本国債(JGB)の利回りは一貫して低下し、最終的にはマイナス圏にまで入った。
しかも、日本政府のグロス政府債務が1990年代初頭のGDP比約70%から、2015年には約250%にまで増加したにもかかわらず、JGB利回りは低下し続けたのである。
日本では、債券利回りが低いまま推移する一方、円は強かった。
しかし利回りが上昇するようになると、円は弱くなった。
つまり、円安と債券利回り上昇の間には相関関係がある。
だが、為替市場に介入するということは、単なる相関だけでなく、そこに因果inga関係があると考えていることになる。
すなわち、円安そのものが債券利回りの上昇を引き起こしていると考えているということだ。
私が考える日本における最大の変化は、食料価格の上昇である。
日本の食料価格は約30年間ほとんど停滞していたが、2013年頃から上昇し始めた。
なぜ日本の食料価格が突然上昇し始めたのかについて、私には確信の持てる説明はない。
しかし、ひとつ確かなことがある。
食料価格が上がれば、賃金chinginも上がらざるを得ない。
もし賃金がそれに追いつかなければ、大きな政治的反発が起きることを覚悟しなければならない。
ひとつの可能性として、日本が食料輸入に依存していることが挙げられる。特に、中国から野菜や果物を多く輸入している。
中国人民元 (RMB)に対して見ると、円は1992年以来の安値yasuneまで下落している。
これは過去とは大きく異なる状況だ。
これまでは通常、円安になると他のアジア諸国も通貨を切り下げる傾向があった。
ところが今回は、中国人民元が強いまま維持されている。
そして、ここが問題の核心なのだと思う。
1980年代、1990年代、そして2000年代を通じて、日本と米国は世界最大級かつ最も豊かな2つの国として、いわば自分たちが世界経済の「天候を決める」ことに慣れていた。
しかし今では、そこに第3のプレーヤーがいる。
中国である。
中国も低金利の国ではある。
だが日本とは異なり、中国は米国債を買うことを選んでいない。
したがって、本当の問題は、中国が通貨を切り下げていないことにある。
その結果、他国、特に日本に対して物価上昇圧力が生じている。
そして同時に、中国は米国債を買うことも選択していない。
では、円が継続的に上昇すれば問題は解決するのだろうか?
もし本当の問題が「人民元が強すぎること」なのであれば、おそらく答えはノーだ。
むしろ円高は、世界の他の地域にさらにインフレ圧力を生み出すだけかもしれない。
中国がかつて世界の商品市場(コモディティ市場)の構造を変えたのと同じように、今度は中国が世界の金融市場の構造を変えつつある。
米国財務省による債券市場や為替市場への介入は、日本と米国が世界の支配的な経済大国だった時代へ時計の針を戻そうとする、叶わぬ願いのように見える。
This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit www.russell-clark.com/subscribe
WHAT JAPAN TELLS US ABOUT US TREASURIES
In the last month or so, the US has announced two separate interventions. One in long dated Treasury market, where buy backs have been increased, and another one, where it intervened in the currency markets to strengthen Yen. The intervention in the long dated bond market is pretty easy to understand, and has some precedence. So far though, no change on bond yields.
The Yen intervention is more interesting. And the intervention did at least a discernible movement in the market.
But how exactly is Yen strength supposed to help the US bond market? I...
THE PROBLEM WITH SUBSTACK
I have been on Substack since 2022, and generally speaking its been pretty good for me. I am on the UK Bestseller rankings, I am slightly above Dan Wotton, but below Dominic Cummings. There is a joke in there somewhere, but it escapes me at the moment. I also do well in the US Bestseller for Finance list.
As a London based bestseller, I have been invited to “Bestseller Summer Drinks”. I was amazed at how young most of the Substack writers were, but ended up talking to one of the other over 50s there - Bria...
TIME FOR BITCOIN?
I know many of the substack/macro community like to pile bitcoin, gold, silver, platinum into a dollar debasement trade. And intellectually that makes total sense. But for the past few years, I have thought GLD/TLT makes more sense (long gold / short treasuries). For me, this felt a much safer trade, than a straight out dollar debasement trade. GLD/TLT has been good, but I wont lie, the 25% drawdown earlier this year did make me nervous.
I know in the more “excitable” corners of substack they have been all in on other debasement trades like bitcoin, silv...
NOT THE BEGINNING OF THE END, BUT PROBABLY THE END OF BEGINNING
Americans love freedom. Perhaps they care about freedom in the rest of the world a bit less these days, but they certainly love freedom in the US. Donald Trump certainly likes the freedom to act as he wishes. Fiscal restraint seems downright un-American. If President Trump wants to run a 6% fiscal deficit, why can’t he?
Other nations have tried to work free from constraint - Turkey now, and Argentina until recently as least. Typically the price of being fiscally liberal has been higher interest rates, and usually a weak currency. Turkish Lira has NOT been a sa...
THE CREDIT MARKETS PUZZLE ME - BUT EQUITIES PUZZLE ME MORE
A few years ago, I ditched a purely macro approach to investing, to incorporate a political angle first. I do not regret this decision. I was away last week, and I was catching up with various emails, and all the “macro” investors remain relentlessly bearish. Most no longer manage funds, but I suspect are chomping at the bit to get back into markets once markets stop “acting funny”, and macro works again.
Politically, markets seem to be doing what I would thought they would so. Growth would be good, and government bond yields would rise. The ONLY issue is...
WHAT'S THE DEAL WITH THE YEN INTERVENTION?
The thing about the US/Japan Yen intervention is that it is less about currencies and more about bond yields. Japanese bond yields have led US bond yields lower for more than half a century. And since 2020, they have been leading US bond yields higher.
The sell off in the long end is basically saying that Japanese short rates remain too low, and should be higher if the BOJ is serious about curtailing inflation. You can see this most clearly in food inflation in Japan. Japan had no food inflation form 1990 to 2013 or...